Ultimately, the framework's success will come down to how well this transition is managed, not just how it's designed on paper.
FinTech BizNews Service
Mumbai, 16 September, 2026: The finalized Merchant Discount Rate (MDR) framework and threshold structure will take effect from 15th October 2026. FAQs on MDR by NPCI make amply clear the applicability of MDR for different stakeholders, including end users of UPI. The MDR is distributed only amongst the UPI ecosystem, to further invest into infrastructure resiliency, innovation, cybersecurity (protecting the UPI Infrastructure with banks and non-banks) and customer service.
A MDR of 0.4% will be introduced on Person-to-Merchant (P2M) UPI transactions above Rs 2,000/-. For transactions of Rs75,000/- and above, the MDR will be capped at Rs300 per transaction. UPI MDR is structured to be much lower than all traditional card-based transaction fees. Standard credit card MDRs typically range from 1.5% to 2.5% per transaction, while debit card MDRs are capped up to 0.90%. By setting the baseline UPI MDR at 0.4% on transaction above Rs 2,000 and capping it at Rs300 for high-value purchases, UPI remains the most affordable digital payment acceptance tool for commercial enterprises.
Demonstrating unprecedented public adoption, UPI processed an astonishing 2,451 crore transactions valued at Rs29.9 lakh crore in August 2026 alone. This immense volume highlights UPI's role as the primary financial engine of the Indian economy, handling hundreds of millions of daily payments. Handling this scale requires massive physical server infrastructure, high-speed telecommunication lines, multi-tiered cybersecurity monitoring, and specialised banking software. These transaction figures reinforce why establishing a self-sustaining funding framework was necessary to guarantee system stability.
Click to know additional useful details: https://fintechbiznews.com/fintech-digital-payment-/mdr-of-04-to-be-applied-on-p2m-upi-txns-above-rs2000
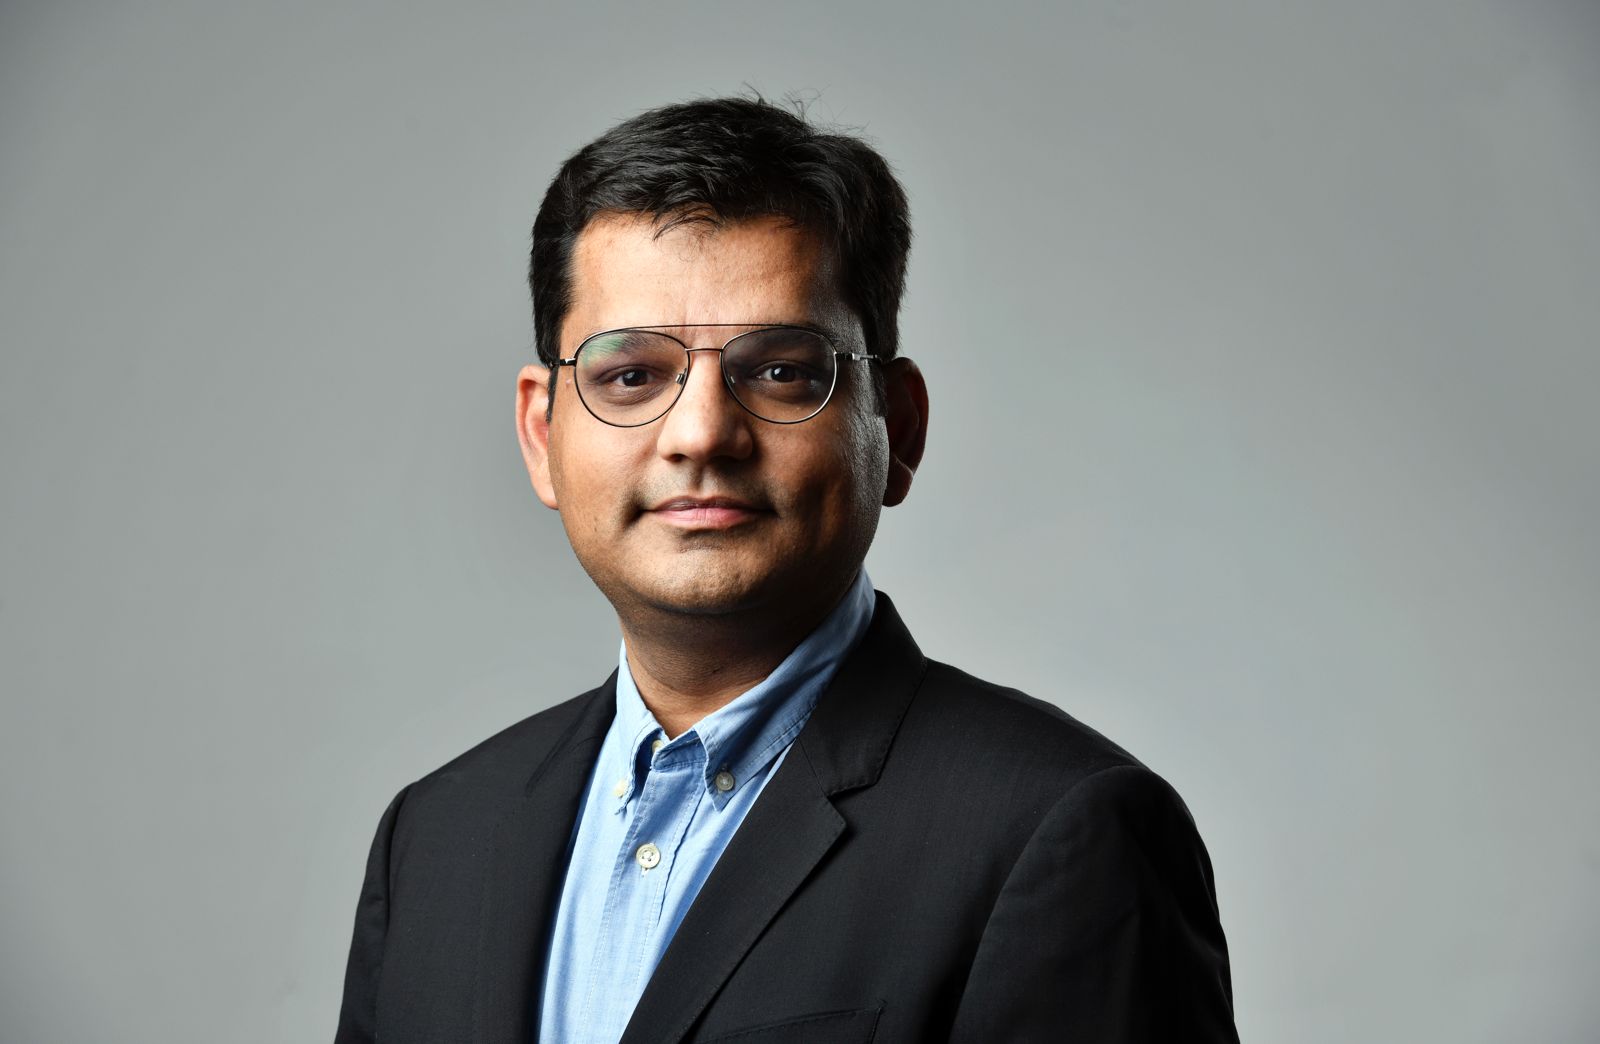
Kunal Jhunjhunwala, Founder, airpay, points out:"The framework is a step toward building a sustainable revenue model for UPI, which matters given the scale of investment banks, fintechs and payment providers have made in building and supporting the ecosystem over the years. The more important question now is whether that revenue is shared fairly across all the players involved. Fintechs, in particular, have driven digital payments deep into the merchant base, often in segments banks found harder to reach, and have invested heavily in the technology and infrastructure that made that possible. That contribution needs to be recognised in how the model is structured, not treated as a footnote.
For merchants, the immediate impact will be the 0.40% MDR on P2M transactions above Rs2,000. Larger businesses will likely absorb this with little friction, but for merchants operating on tight margins, even a small percentage can change how they think about accepting digital payments. The bigger challenge, though, is timing. Fintechs now have roughly a month to explain the new cost to merchants, help them get comfortable with it, and make the backend changes needed to support it. That's a short runway for a change with this much reach.
Ultimately, the framework's success will come down to how well this transition is managed, not just how it's designed on paper. What the ecosystem needs is a model that works for merchants on the ground while giving fintechs and other payment providers enough room to keep investing in what makes UPI reliable, secure and easy to use. Once we get that transition right, MDR becomes a foundation for UPI's next stage of growth rather than a friction point."
Click to read more views on the subject: https://fintechbiznews.com/fintech-digital-payment-/rupay-acquiring-business-will-be-dead-ketan-doshi
https://fintechbiznews.com/fintech-digital-payment-/upi-needs-economic-model-to-aid-its-scale-patel